Buying a new launch condo in Singapore runs on a fixed clock, not a flexible one. Day 1 starts the moment you pay the booking fee and receive your Option to Purchase (OTP). From there, you exercise the OTP and sign the Sale and Purchase Agreement, then face the single deadline that trips up more buyers than anything else: paying your remaining initial downpayment within 8 weeks from the Date of Option. After that, progressive payments follow construction milestones through to TOP and CSC. Everything else, including Buyer's Stamp Duty and ABSD, follows rules set by IRAS) and the Housing Developers Rules.
TL;DR:
- The 8-week deadline to pay the remaining initial downpayment is critical; failure to secure an extension may result in losing your option money.
- Construction milestone payments typically encompass around 10 stages, including foundation, structural work, roofing, fittings, and final TOP and CSC stages.
- Early mortgage approval, submitting documents promptly, and coordinating disbursements with your bank are key to meeting the tight 8-week window.
- Missing the 8-week downpayment deadline often stems from financing delays, late solicitor processing, or developer paperwork, making early planning essential.
- The timeline is based on industry-standard schedules and statutory rules, emphasizing the importance of scheduling buffer days and proactive preparation.
Table of Contents
- What Is the Step-By-Step New Launch Timeline?
- How Does the Progressive Payment Schedule Work?
- When Are Stamp Duties and Legal Steps Due?
- What Financing Steps Must You Finish in 8 Weeks?
- What Causes New Launch Timelines to Slip?
- What Happens at TOP and Final Handover?
- Where This Timeline Comes From
- Why Early Planning Beats a Perfect Spreadsheet
- See How This Timeline Plays Out at Aurea
- Sources
- FAQ
What Is the Step-By-Step New Launch Timeline?
The sequence below is what most buyers experience, though developers can adjust minor dates. Treat it as your master checklist and copy it straight into your calendar the day you pay your booking fee.
- Day 1: Pay the booking fee, receive your Option to Purchase, appoint a solicitor, and submit your mortgage application the same week.
- Within 2 weeks: The developer's law firm circulates the Sale and Purchase Agreement (S&P). Your solicitor reviews the draft and flags any title or encumbrance issues.
- Within 3 weeks of S&P delivery: Exercise the OTP and sign the S&P. Some developers set a slightly different window, so confirm the exact date printed on your OTP.
- Within 8 weeks from the Date of Option: Pay the remaining initial downpayment in cash or CPF, or secure a written extension from the developer before the deadline passes.
- Construction milestones onward: Progressive payments are billed as the building hits certified stages, continuing until Temporary Occupation Permit (TOP) or Certificate of Statutory Completion (CSC).
This mirrors the practical structure described in industry timeline guides, and it's worth building in a few days of buffer around each step. Product teams outside real estate use the same logic. Atlassian's launch planning framework recommends working backward from a fixed date and padding every milestone, which applies just as well to a condo purchase as it does to a software rollout.
How Does the Progressive Payment Schedule Work?
New launch condos in Singapore don't get paid off in one lump sum. Payments are staged by law under the Housing Developers Rules, and each stage is tied to a certified construction milestone rather than a calendar date. That structure protects buyers, since you're only paying for work the developer has actually completed and verified.
Everything after that follows the build.
| Stage | Typical Trigger | Approximate Share of Price |
|---|---|---|
| Booking fee | OTP issued | a small percentage |
| Balance to total for initial payment | Within downpayment deadline period | remainder of initial payment |
| Foundation work | Certified milestone | progressive payment |
| Structural work (multiple stages) | Certified milestones | progressive payments |
| Roofing/brick walls, ceiling | Certified milestones | progressive payments |
| Doors, windows, fittings | Certified milestones | progressive payments |
| Road, drainage works | Certified milestones | progressive payments |
| TOP | Temporary Occupation Permit issued | major payment stage |
| CSC | Certificate of Statutory Completion | final payment stage |
Percentages here reflect the standard 10-stage structure buyers commonly encounter, which PropertyGuru's payment schedule breakdown sets out in full. Every developer's exact split can vary slightly, so always check the schedule attached to your specific S&P.
- Cash and CPF can typically both be used for the early stages, subject to CPF withdrawal limits.
- Bank loan disbursements are usually released stage by stage, matching each developer claim rather than paid out in advance.
- Confirm with your bank exactly how their disbursement timing lines up with the developer's billing, since a mismatch here causes real delays later.
Pro Tip: Ask your bank for a written disbursement schedule at the same time you get your in-principle approval. It's the fastest way to catch a timing gap before it becomes a late payment.
When Are Stamp Duties and Legal Steps Due?
Buyer's Stamp Duty (BSD) is payable within 14 days of exercising the OTP if signed in Singapore, and current rates and bands are set out on IRAS's BSD page. Additional Buyer's Stamp Duty (ABSD) may also apply depending on your residency status and how many properties you already own, with full rules and remissions detailed on IRAS's ABSD page. If you're mapping out exact figures against your purchase price, a stamp duty checklist built for new launch buyers helps you sanity check the math before your solicitor files anything.
- Your solicitor reviews and finalizes the S&P, lodges the stamping instrument, and coordinates the actual duty payment on your behalf.
- They also confirm the title is clean and free of unexpected encumbrances before you commit further funds.
- Missing the stamp duty deadline or the 8 week downpayment deadline can put part or all of your option money at risk, so get official confirmation from IRAS or your solicitor rather than guessing.
What Financing Steps Must You Finish in 8 Weeks?
The 8 week window from your Date of Option is the busiest stretch of the entire process, and mortgage readiness is the factor that trips up the most buyers.
- Get bank in-principle approval before, or immediately after, paying your booking fee.
- Submit full income and identity documents to your bank and solicitor early so the loan offer and valuation land in time for the S&P exercise.
- If using CPF for your downpayment, prepare and submit your CPF forms early, ideally in coordination with your lawyer rather than at the last minute.
- Keep contingency cash on hand in case your loan payout timing doesn't quite match the developer's claim schedule.
Buyers who lock in MAS-regulated bank approval early, and align valuation timing with their solicitor's readiness, are the ones who consistently clear the 8 week deadline without needing an extension.
Pro Tip: Don't wait for your S&P to arrive before contacting your bank. Start the loan conversation the same day you pay your booking fee.
What Causes New Launch Timelines to Slip?
Most delays trace back to one of three things: a financing shortfall, a solicitor buried in other files, or developer paperwork arriving later than expected.
- If you're going to miss the 8 week deadline, request an extension from the developer in writing before the deadline, not after.
- Extensions are usually granted at the developer's discretion and often come with a fee or interest charge on the outstanding balance.
- Appointing your solicitor on Day 1, rather than waiting for the S&P to land, is the single easiest way to avoid a self-inflicted delay.
- Keep contingency cash available and get your lender's disbursement timeline in writing so a mismatch doesn't catch you off guard.
What Happens at TOP and Final Handover?
Loan disbursement is normally timed to release alongside this claim, so confirm with your bank a few weeks ahead that everything's ready to move.
- Walk the unit and compile a snag list covering finishes, fittings, and any visible defects before signing off.
- Test every utility, including water pressure, electrical points, and air-conditioning, while you're still on-site.
- Complete final progressive payments through TOP and CSC as each certified stage is billed.
- Lodge any defects formally with the developer within the defects liability period, which typically runs for a set duration after handover and covers workmanship issues that surface after you move in.
Where This Timeline Comes From
This timeline draws on the practical sequencing developers publish for new launches, plus the statutory framework IRAS and the Housing Developers Rules put in place for every project in Singapore. For a real-world example of how milestones map to an actual development, Aurea's Latest Updates page tracks the project's own construction progress at 802 Beach Road, an 188-unit tower with 2 to 5 bedroom layouts and two penthouses, developed by GMC Property Pte. Ltd., set for completion in 2029.
- Cross-check any percentage split against your own S&P before treating it as final.
- Budgeting guides on cash downpayment planning help you stress-test your own cashflow against the 8 week deadline.
- Project-specific proof points, testimonials, and case studies from actual buyers are best confirmed directly with the developer's marketing team.
Why Early Planning Beats a Perfect Spreadsheet
Buyers who treat the 8 week window as a countdown, not a suggestion, tend to sail through it. The ones who get stuck usually didn't lock in bank approval until after their S&P arrived, then scrambled when the valuation ran late. One buyer we've seen referenced in developer case discussions simply appointed a lawyer and submitted mortgage paperwork on the same day as booking, and cleared the entire deadline with two weeks to spare. That's the whole trick: start the boring paperwork before you feel ready to.
— Velisa
See How This Timeline Plays Out at Aurea
If you're weighing a new launch purchase against resale or other options, Aurea gives you a concrete example of what this entire timeline looks like in practice, right down to the payment stages and construction milestones described above. Located at 802 Beach Road, this new development offers units from 2 to 5 bedrooms plus two penthouses, with resort-style amenities spread across multiple levels and a link bridge to The Golden Mile, all within reach of multiple MRT stations.
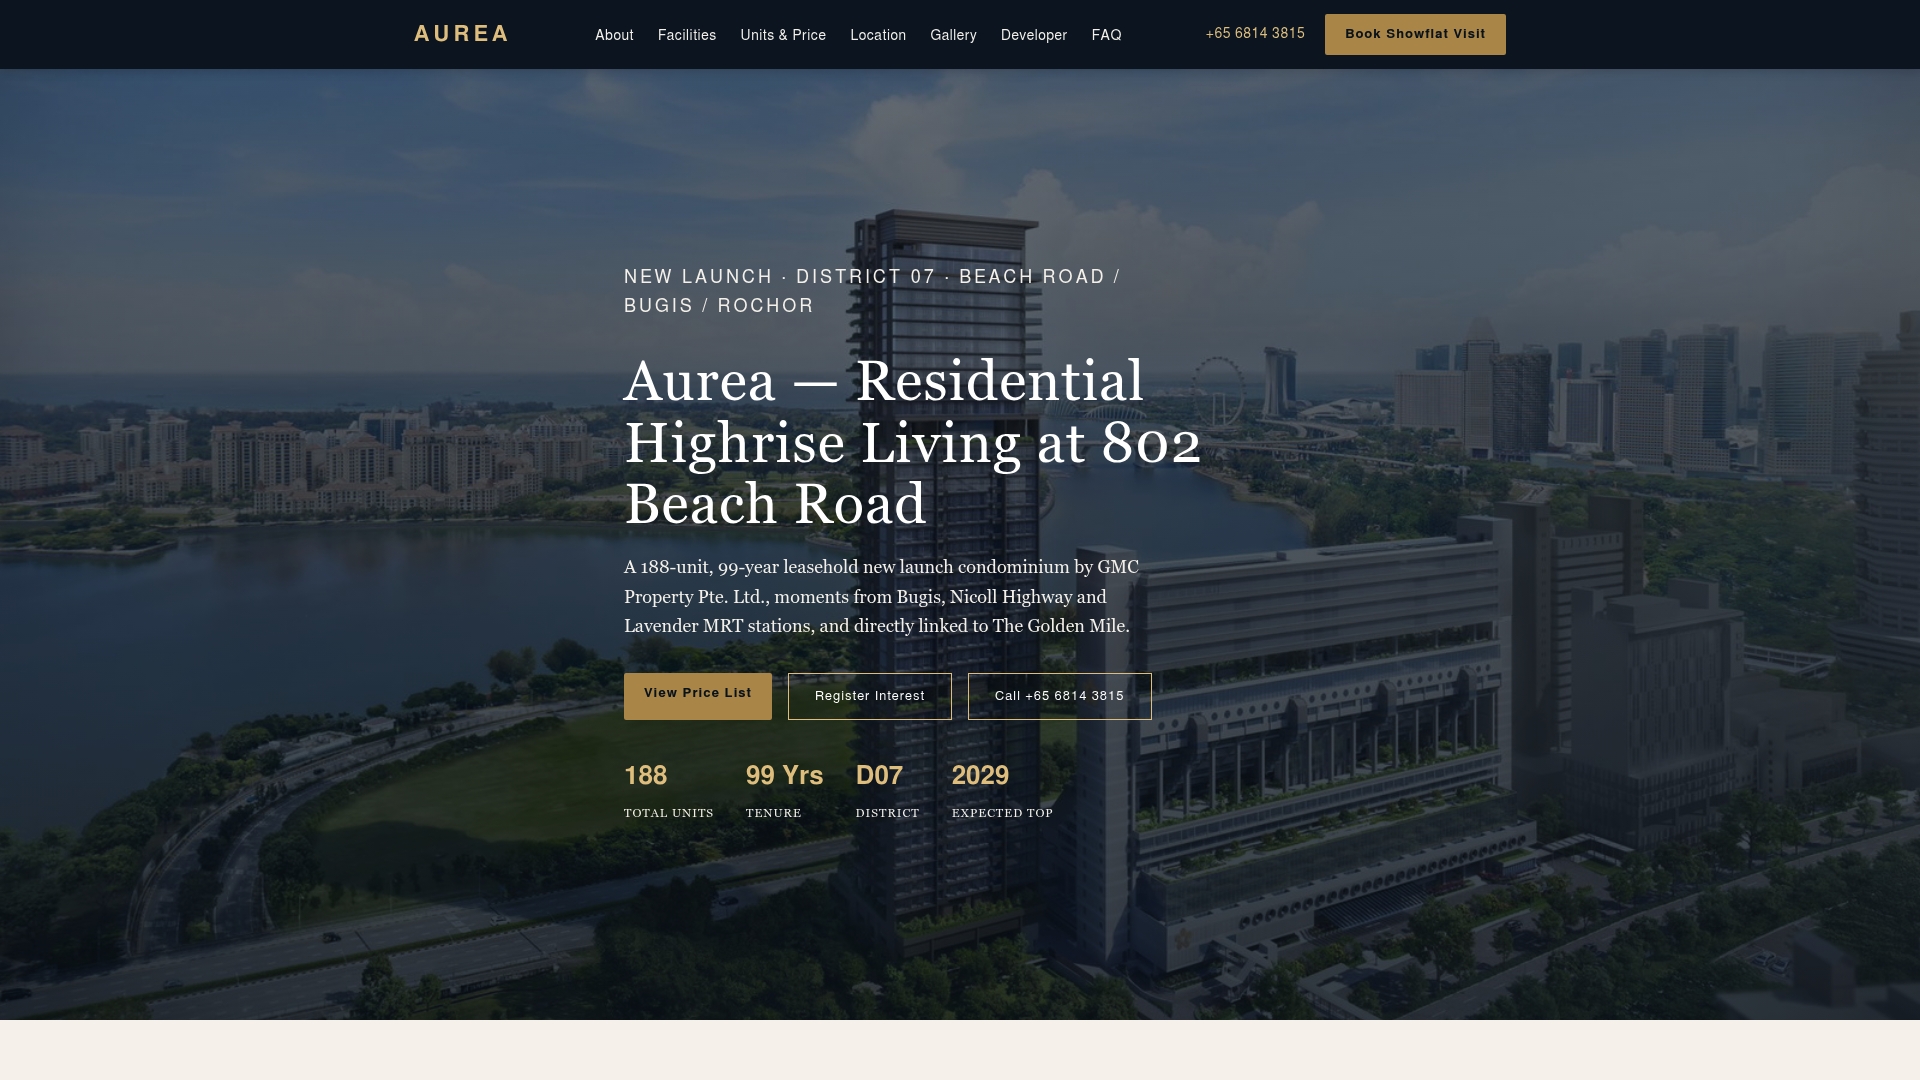
The unit mix suits different household sizes, from young professionals to multi-generational families, rather than a one-size-fits-all layout stretched across every floor. If you're ready to see how your own 8 week window and payment schedule would map onto a specific unit, visit Aurea's Latest Updates page to check showflat availability and get in touch with the marketing team directly.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Urban Redevelopment Authority (URA)
- Timeline for Purchasing a New Launch or Uncompleted Project in Singapore
- Condo progressive payment schedule: all 10 stages, from booking to CSC | PropertyGuru
FAQ
What Is the Typical Timeline for Buying a New Launch Condo?
It runs from Day 1 booking and OTP, through S&P exercise within roughly 3 weeks, to a remaining downpayment due within 8 weeks from the Date of Option, then progressive payments through construction until TOP and CSC.
How Long Do I Have to Exercise the Option to Purchase?
Most developers set a 3 week exercise window from S&P delivery, though the exact date is printed on your OTP and should always be confirmed against that document.
When Is Stamp Duty Due on a New Launch Purchase?
Buyer's Stamp Duty is generally due within 14 days of exercising the OTP, with rates and any Additional Buyer's Stamp Duty obligations set by IRAS.
What Are the Upcoming New Launches in Singapore?
This project at 802 Beach Road is one current example with its own published construction and payment schedule on its updates page.
What Happens if I Miss the 8-Week Downpayment Deadline?
You risk forfeiting part or all of your option money unless you secure a written extension from the developer before the deadline passes, so request one in advance rather than after the fact.